A structural engineer report for mortgage purposes is often requested when a lender valuer spots cracking, movement or alterations that they cannot judge on a short valuation visit. For a buyer, it can feel like the whole purchase has stalled overnight. The good news is that most cases follow a predictable path, and knowing each stage in advance makes it far easier to keep the sale moving and avoid unnecessary delays.
This guide follows the lender process as a timeline. It explains why lenders ask for a structural report for mortgage approval, what usually triggers the request, the six stages from valuer referral to lender decision, who can write the report, what it should contain, typical costs and timings and how to avoid delays. It is written for buyers, sellers and brokers in Liverpool, Merseyside and the North West.
In this guide
- Why lenders ask for a structural report
- What triggers a referral
- The six stage timeline
- Who can write the report
- What happens at the inspection
- What the report should contain
- Possible lender decisions
- Common issues behind the request
- Cost and turnaround
- Valuation, survey or engineer report
- How to avoid delays
- What to do after the report
- Advice for sellers
- Structural reports in Liverpool
- FAQs
Why Lenders Ask for a Structural Engineer Report for Mortgage Approval
A mortgage lender is lending against the value of the property. Before releasing funds, the lender instructs a valuer to confirm that the home is suitable security for the loan. A mortgage valuation is a short inspection focused on value, not a detailed survey. If the valuer sees signs of movement or structural alterations that could affect value or saleability, they will usually recommend further specialist advice rather than guess.
The lender then asks for a structural engineer report for mortgage purposes. The aim is simple. The lender wants a qualified professional to confirm whether the movement is historic or ongoing, whether repairs are needed and roughly what they might cost. Until that question is answered, many lenders will pause the offer or hold back part of the loan.
It is worth remembering that the report is not only for the lender. It gives the buyer independent evidence about the condition of the home, which is valuable when deciding whether to proceed and at what price.
What Triggers a Structural Report for Mortgage Purposes
Every lender has its own criteria, but these are the most common triggers.
- Cracks in walls, especially diagonal or stepped cracks, or cracks that are wider at one end.
- Doors and windows that stick or frames that look distorted.
- Bulging or leaning walls, including gable walls and bay windows.
- Signs of subsidence, heave or past underpinning.
- A chimney breast removed without visible support above.
- Walls removed to create open plan rooms, without evidence of approval.
- Roof spread, sagging ridges or distorted roof lines.
- Non standard construction or unusual building methods.
- Large trees close to the house on clay soil.
Our guide to cracks in walls explains how crack patterns are read, and our page on chimney breast removal covers one of the most common alteration issues lenders raise.
The Six Stage Timeline
The timeline below shows how a structural engineer report for mortgage approval usually progresses, from the moment a valuer flags a concern to the moment the lender makes a decision. Timings are typical and depend on the lender, the engineer and the property.
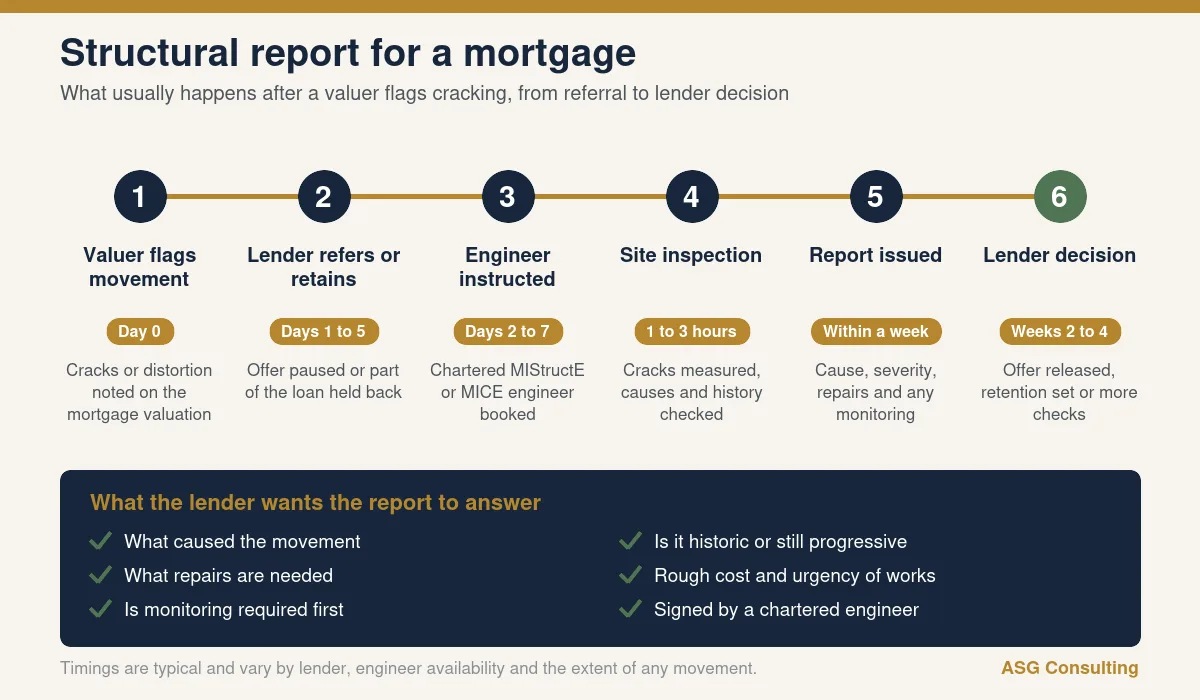
1. The valuer flags movement
During the mortgage valuation, the valuer notes cracking, distortion or alterations. The valuation report will often say that a structural engineer report for mortgage purposes is required before the lender can proceed, or that the valuation is subject to a satisfactory report.
2. The lender refers or retains
The lender reviews the valuation. It may pause the mortgage offer until a report is received, or issue an offer with a retention, which means part of the loan is held back until works are carried out or confirmed. Your broker or lender should tell you exactly what is required.
3. A structural engineer is instructed
The buyer usually instructs and pays for the engineer. Some lenders specify the qualifications the engineer must hold, so check the wording carefully before booking. Make sure the engineer knows this is a structural report for mortgage approval and has a copy of the relevant part of the valuation.
4. The site inspection
The engineer visits the property, inspects the areas of concern and looks for evidence of the cause. A typical visit takes one to three hours, depending on the size of the home and the extent of the issues.
5. The report is issued
The engineer writes a report explaining the findings, the likely cause, whether the movement is progressive and what repairs or monitoring are needed. Reports are often issued within a few days to a week of the visit.
6. The lender makes a decision
The buyer or broker sends the report to the lender, who then decides whether to release the offer, set or adjust a retention, ask for further checks or decline. The lender may also ask its valuer to review the report.
Who Can Write a Structural Engineer Report for Mortgage Use
Lenders generally want a structural engineer report for mortgage use to come from a suitably qualified and insured professional. The Home Owners Alliance guide to structural engineer inspections recommends using a chartered engineer who is a member of the Institution of Structural Engineers or the Institution of Civil Engineers, shown by the letters MIStructE or MICE.
Some lenders accept reports from other qualified professionals, such as chartered building surveyors, for certain types of defect, but this varies. Always check the exact wording of the lender requirement before you instruct anyone. Our guide on how to check structural engineer credentials explains how to confirm membership and insurance.
What Happens at the Inspection
During a structural engineer report for mortgage inspection, the engineer focuses on the issue raised by the valuer, but looks at it in the context of the whole building. A typical inspection covers the following.
- Measuring and recording the width, direction and pattern of cracks.
- Checking walls for leaning or bulging with a level or plumb line.
- Looking at doors, windows and floors for signs of distortion.
- Inspecting the outside for drainage problems, trees and ground levels.
- Checking alterations such as removed walls or chimney breasts.
- Reviewing any history provided, such as past repairs or insurance claims.
The engineer may not be able to lift floors or open up walls without the seller agreeing. If something cannot be inspected, the report should say so and explain any further checks recommended.
What the Report Should Contain
A useful structural report for mortgage approval answers the questions the lender is likely to ask. The table below shows the main sections and why each matters.
| Section | What it tells the lender |
|---|---|
| Description of the property | Age, construction type and any alterations |
| Observations | Where the cracks or movement are, with measurements and photos |
| Likely cause | Such as settlement, subsidence, lintel failure or wall tie corrosion |
| Historic or progressive | Whether the movement appears to have stopped or may continue |
| Recommendations | Repairs needed, with priority and urgency |
| Cost guide | A rough idea of repair costs where the lender asks for one |
| Monitoring | Whether crack monitoring is advised before a final view |
| Signature and qualifications | Confirms the report is from a suitably qualified engineer |
A report that answers these points clearly is much more likely to satisfy the lender first time.
Possible Lender Decisions
Once the lender receives the structural engineer report for mortgage review, these are the most common outcomes.
- Offer released. The movement is historic and stable, and no further action is needed.
- Retention. Part of the loan is held back until specified repairs are carried out and signed off.
- Conditions. The lender asks for repairs, specialist checks or a guarantee before or after completion.
- Monitoring. The engineer recommends crack monitoring over several months before a final view, which can delay the purchase.
- Decline. In rare cases, such as active subsidence or serious defects, the lender may decide not to lend on the property.
If monitoring or major repairs are needed, it may be worth discussing a price reduction or a delay with the seller. Our guide on renegotiating after a survey explains how to approach that conversation.
Common Issues Behind the Request
Most requests for a structural engineer report for mortgage approval come back to a small number of recurring defects. The table below shows the issues we see most often and what the engineer will usually be asked to confirm.
| Issue | Lender concern | Typical recommendation |
|---|---|---|
| Historic settlement cracks | Is the movement still active | Often no action beyond minor crack repair |
| Possible subsidence | Could the foundations keep moving | Drain checks, monitoring or an insurer investigation |
| Removed chimney breast | Is the stack above properly supported | Evidence of support or new steelwork with approval |
| Removed internal wall | Is the opening supported and signed off | Inspection of the beam and building control records |
| Bay window movement | Is the bay separating from the house | Repair, tying in or monitoring |
| Wall tie corrosion | Is the outer leaf becoming unstable | Wall tie survey and replacement ties |
Knowing which of these applies helps you choose the right engineer and brief them properly, which in turn makes the structural report for mortgage review quicker for the lender.
Structural Engineer Report for Mortgage Cost and Turnaround
The cost of a structural engineer report for mortgage use depends on the size of the property, the issue and how detailed the report needs to be. The Home Owners Alliance notes that some structural inspections cost around 300 to 400 pounds or more. Larger homes, complex issues or reports needing calculations or drawings will cost more.
In terms of timing, the visit itself usually takes one to three hours, and many engineers issue the report within a few days to a week. The lender then needs time to review it. Booking quickly and sending the engineer the valuation wording in advance are the best ways to keep the process short.
Valuation, Survey or Engineer Report
Buyers are often confused about how a structural report differs from other inspections.
| Inspection | Who it is for | What it covers |
|---|---|---|
| Mortgage valuation | The lender | Value and suitability as security, not condition in detail |
| Home buyer survey | The buyer | Condition of a conventional home, with defects rated by urgency |
| Building survey | The buyer | A detailed look at condition, suitable for older or altered homes |
| Structural engineer report | Buyer and lender | A focused assessment of a specific structural concern |
A good full home buyers survey carried out early can spot structural concerns before the lender valuer does, which gives you more time to arrange an engineer if needed.
How to Avoid Delays with a Structural Report for Mortgage Approval
A structural report for mortgage approval does not have to derail a purchase. These steps help keep things moving.
- Ask your broker or lender for the exact wording of the requirement.
- Book a suitably qualified engineer as soon as the request arrives.
- Send the engineer the relevant section of the valuation and any photos.
- Ask the seller for any history of past movement, repairs, underpinning or insurance claims.
- Arrange access quickly through the estate agent.
- Check the draft report answers every point the lender raised.
- Send the final report to the lender promptly and follow up.
What to Do After the Report
Once you have the structural engineer report for mortgage use, read it carefully before sending it on. Check that it addresses every point in the valuation, that the property address is correct and that it is signed by the engineer named in the lender requirement.
If repairs are recommended, get written quotes from suitable contractors as soon as possible. Lenders that set a retention usually want evidence that the work has been completed, such as an invoice, a completion letter from the engineer or building control sign off. Ask your lender exactly what it needs to release the retention so there are no surprises later.
Keep a copy of the report, the quotes and any completion paperwork with your property records. When you come to sell, a future buyer lender may raise the same question, and having a clear history of the issue and the repairs can save weeks.
If the report reveals more serious problems than expected, take time to think before proceeding. You can ask the seller to reduce the price, to carry out repairs before completion or to wait while monitoring takes place.
Advice for Sellers
If your home has visible cracks, alterations or a history of movement, a buyer lender may well ask for a report. Sellers can reduce delays by gathering paperwork in advance, such as building regulations approvals, structural calculations, underpinning guarantees and insurance claim records. Where there is old, stable cracking, some sellers choose to commission their own engineer report before marketing, so buyers and their lenders can see the facts from the start.
If movement is linked to subsidence, our guides to subsidence surveys and underpinning explain what lenders and insurers usually look for.
Structural Reports in Liverpool
Liverpool and Merseyside have many Victorian and Edwardian terraces, interwar semis and converted flats. Common reasons for a structural engineer report for mortgage approval in the area include historic settlement cracks in older terraces, bay window movement, failed lintels, wall tie corrosion in cavity walls and removed chimney breasts or internal walls.
Most of these issues are historic and stable, and a clear structural report for mortgage approval usually allows the lender to proceed. Where repairs are needed, such as replacing a cracked lintel or dealing with wall tie failure, the report gives the buyer a clear scope of works to price and negotiate on.
Structural Report for Mortgage FAQs
Who pays for a structural engineer report for mortgage purposes?
The buyer usually pays, because the report is needed for their mortgage. Some buyers ask the seller to share the cost or reduce the price if significant repairs are found.
Can I use a report the seller already has?
Sometimes. Lenders usually want a recent report addressed to them or the buyer, so check with the lender before relying on an older report.
How long does a structural report for mortgage approval take?
The visit often takes one to three hours, and the report is commonly issued within a few days to a week.
Does needing a structural report for mortgage approval mean the house is unsafe?
No. Most reports find historic movement that has stopped. The lender is simply asking for an expert view before lending.
What if the engineer recommends monitoring?
Monitoring can take several months. Talk to the seller and lender about timescales, a retention or a price adjustment.
Can a chartered surveyor write the report?
Some lenders accept a report from a chartered building surveyor for certain defects, but many specify a chartered structural engineer. Check the lender requirement first.
Will the report be shared with the seller?
The report belongs to the person who paid for it, usually the buyer. You can choose to share it with the seller to support a renegotiation.
Book a Structural Engineer Report in Liverpool
ASG Consulting is regulated by RICS. We arrange structural inspections and reports for buyers, sellers and brokers across Liverpool, Merseyside and the North West, written clearly so lenders can make a decision quickly. To find out more, visit our residential structural engineer page.
About the Author
Harry is a property content writer with 3 years of experience writing about building surveying, commercial property and property compliance in the UK. He writes the guides at ASG Consulting for buyers, tenants and landlords, turning survey practice into clear, practical advice.
Reviewed by Dave MacMillan MRICS, chartered surveyor at ASG Consulting. Dave checks the technical content of our guides against current RICS practice before they are published.
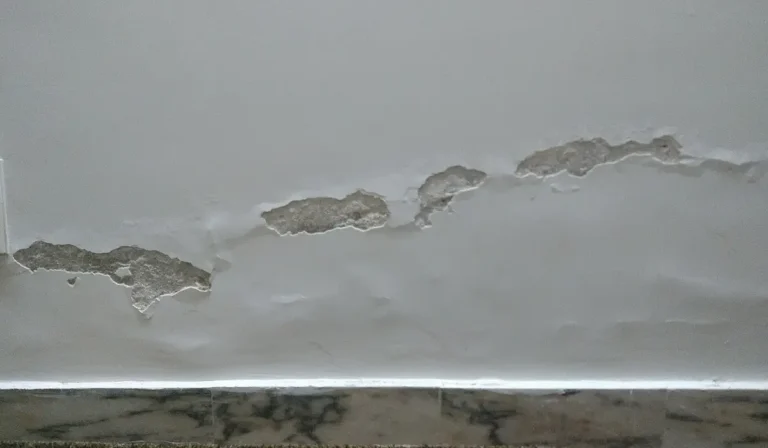
Featured photo of a cracked wall by Almanta via Wikimedia Commons, licence CC BY SA 4.0, cropped.